

Hi everyone, Dave here.
Today’s issue is a first for us. I’m sharing it with someone else.
I want to introduce you to Max, the founder of MaxDividends. The dividend corner of Substack is small, and Max is one of the best (arguably the best) in our little corner. He has built one of the best dividend investing communities out there by publishing real research every week for years. He is what I want to be when I grow up.
One of the many things I admire about Max is that he runs an actual system. The MaxDividends Income System scores every company on business quality and dividend safety before he will even consider owning it, and he shows you the scores. Complete transparency, which is refreshing in the investing world.
He also focuses on helping people grow dividends to pay the bills, which is what we are trying to do too.
Check out his newsletter:
A few weeks back, Max and I got on a call that was supposed to run 30 minutes and went a lot longer. Somewhere in there, he floated an idea.
Max: Dave, what do you think about writing a research report together? Let’s pick one company that meets both your framework and the MaxDividends framework.
Dave: I love that idea. Let’s do it.
Well, here we go…..
Today’s report is the result of that collaboration—a complete research report on a company that successfully passed two independent quality frameworks and earned its place on both of our watchlists.
Consider this our complimentary joint Dividend Research Report. Enjoy!
Dave & Max Joint Research Report: Domino’s Pizza (NYSE: DPZ) 🍕
One Company. Two Independent Frameworks.
The headline wasn’t lying. We deliberately picked a company that’s a little outside today’s market hype. But that’s often where the most interesting long-term opportunities are found.
Our shortlist started with 15 companies. Then we narrowed it down to 6. Then 3. And in the end, we both landed on the same business. Well... partly because we both happen to love pizza.
I will kick things off by walking through my framework and explaining why Domino’s earned a place on my list.
Then Max will walk you through the company using the MaxDividends framework and show you how he reached the same conclusion from a different angle.
Here I go.
Dave Analysis
Most think Domino’s ($DPZ) sells pizza, and they are not wrong. But the business model revolves around franchises and the pizza (while great) drives growth.
The company sells around $20 billion in pizza, but records revenues of $5 billion+.
That gap is the whole business, so let’s start there.
🟢 Business quality

Domino’s does not sell pizza. It franchises pizza, and it supplies pizza.
The franchise model works like this: the company owns 186 stores, with franchises of 22,531. The franchisees put their own money up to build the stores and collect all the money from sales. They pay Domino’s a 5.5% royalty, while the franchisees buy their dough, cheese, and boxes through the 22 US supply chain centers.
Here’s where FY2025 profit came from:
US stores: $1,611.8M revenue, $575.3M segment income (48.6% of profit)
Supply chain: $2,989.5M revenue, $320.1M segment income (27.0% of profit)
International franchise: $338.7M revenue, $288.5M segment income (24.4% of profit)
The international line is the standout. It throws off 6.9% of revenue and a quarter of the profit at an 85% margin, because a royalty check costs almost nothing to collect.
And this detail from the 10-k is interesting. Domino’s hands its franchisees 50% of the pre-tax profit from the supply chain centers. Franchisees are not obligated to buy from Domino’s, but the vast majority do because they own half the upside.
That is a supplier relationship almost nobody else in franchising has and is part of the genius of the model.
FY2025 free cash flow was $671.5M, up 31% from $512.0M.
One warning before you screen this company. Return on Equity will look like crap because of 20 years of borrowing to buy back stock. The ROE screeners will show negative $3.98B in shareholders’ equity.
Do the calculations by hand; with around $745M of after-tax operating profit on about $590 of net operating capital, we see a better ROE. All because the stores are funded by someone else.

🏰 The moat
The moat protecting the business revolves around three things. And one of gets stronger every year.
The advertising fund. US franchisees pay 6% of sales for a national ad fund, collecting $559.5M in 2025, up 9.7%. By comparison, Pizza Hut’s is under $5B and shrank 8.2% last year, and Papa John’s is around $3.7B and falling. Those companies' ad funds are a cut of the system sales, so the marketing budgets shrink while Domino's grows.
The supply chain. Margins grew from 9.04% in 2023 to 10.71% in 2025. That expansion is what pays for the $9.99 promotions without crushing franchisee profit.
The loyalty program. 37.3 million active members. The 2023 relaunch dropped the earning threshold to $5 to grab carryout customers, and carryout comps ran +6.5% in Q4 2025 against delivery at +1.6%.
Moats don't go from strength to strength; we have to look for chinks too.

The US QSR pizza category shrank about 0.3% in 2025 while Domino’s US retail sales grew 4.8%. So the outperformance is share taken from Pizza Hut and Papa John’s. The downside to this, share taken from shrinking competitors, is a finite resource.
Domino’s also spent twenty years teaching pizza delivery meant its own app and its own drivers, then joined Uber Eats and DoorDash. The store economics survive that, because Domino’s charges more on the apps and still drives every order itself. What does not survive is owning the screen where the customer decides.
The first half of 2026 showed the strain:
Q1 2026 US same-store sales: +0.9%
Q2 2026 US same-store sales: +0.1%
Q2 2026 delivery comps: −0.7%
CEO Russell Weiner blamed a premium pizza launch whose “messaging wasn’t compelling enough.” Joe Jordan takes over as CEO on October 1.
I score the moat as wide and durable. I also think the growth runway is shorter than the “Hungry for MORE” plan advertises.
🛡️ Dividend safety

Dividend Safety Score: 3.9 / 5 (Healthy)
Free cash flow payout: 35%
Earnings payout: 39%
Interest coverage: 4.9x
Return on invested capital: 51%
Dividend growth streak: 12 years
Five-year dividend CAGR: +17.4%
The payout is the easy part. Domino’s paid $236.9M in dividends out of $671.5M of free cash flow in FY2025 and still had room for $357.7M of buybacks on top.
The debt is what holds this at 3.9 and keeps it from scoring higher. Domino’s carries $4.88 billion of notes against $165M of cash, at 4.3x leverage.
None of that threatens the dividend. A 35% free cash flow payout covers it easily. But pay attention to the debt and interest coverage, for any sign of trouble.
💲 Valuation
At $347.44, Domino’s trades near its cheapest valuation of the past ten years.
P/E: 19.7x (five-year average 26.5x)
Price to free cash flow: 17.6x (five-year average 26.7x)
Free cash flow yield: 5.69% (five-year average 3.91%)
Since 2021, Dominos has grown earnings 29%, while the share price dropped 35%, indicating multiple compression with no business decline.
Using a reverse DCF, and following inputs:
TTM free cash flow of $653.4M
Discount rate of 9%
Terminal growth rate of 3%
The current market cap of $11.5B implies 3.3% annual free cash flow growth for the next decade.
The market is pricing Domino’s for around inflation. When you consider Domino's has compounded free cash flow at 8% a year since 2019, and the company’s guidance calls for 8% operating income growth, it looks like a mispricing to me.
One honest caveat. My 9% discount rate is a choice (roughly around the WACC or the company’s cost of capital), and at 8% the implied growth drops to 1.0% while at 10% it rises to 5.4%.
✅ My verdict
Buy, with the 2027 refinancing on the watch list.
Plus side:
99% franchised stores
85% international margins on royalties
Supply chain that shares profits with franchisees
11 years of share gains
FCF growth of 11% in 2025.
What changed is the price, and the reverse DCF says the market now wants 3.3% growth out of a business delivering double that.
Two things I’m watching:
US comps recover above 2%
Whether Joe Jordan resets the 2028 targets when he takes over.
I own this great company and will continue to add on weakness.
Max Analysis
How I Analyze Dividend Stocks
For today’s analysis, I’m using the MaxDividends Income System inside the MaxDividends Research Platform - the same framework I use every week to evaluate every company before adding it to my portfolio.
🟢 Business Quality
Every company first has to prove it’s a great business before I even look at the dividend. The Business Quality Score is built around five core areas:
📈 Consistent sales growth
💰 Growing profits
🏦 Strong net income
💵 Healthy dividend coverage
⚖️ Conservative debt levels
✅ DPZ Business Quality Score: 97/99 — Very Safe
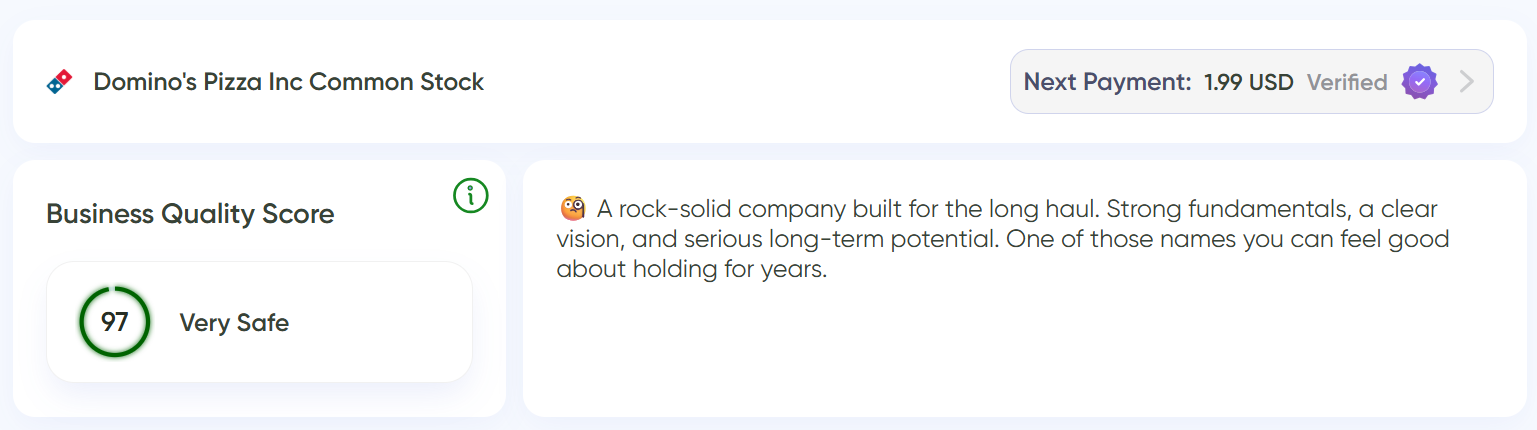
Domino’s scores 97 out of 99, placing it firmly in the Very Safe category.
🛡️ Dividend Safety
A great business doesn’t automatically make a great dividend stock. Our Dividend Safety Score combines four key factors:
Business Quality
Dividend policy and consistency
Payout sustainability
Long-term dividend growth
✅ DPZ Dividend Safety Score: 97/99 — Very Safe
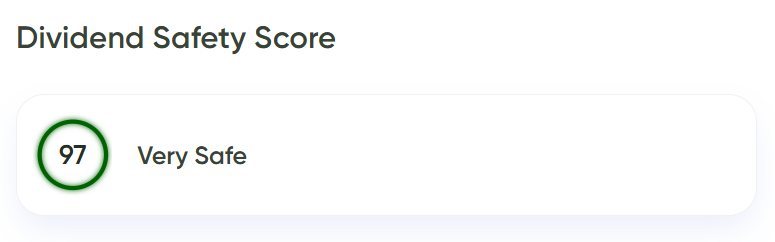
Domino’s scores 97/99, giving me confidence that today’s dividend remains well supported by the business.
💲 Valuation
That conclusion comes from two independent checks:
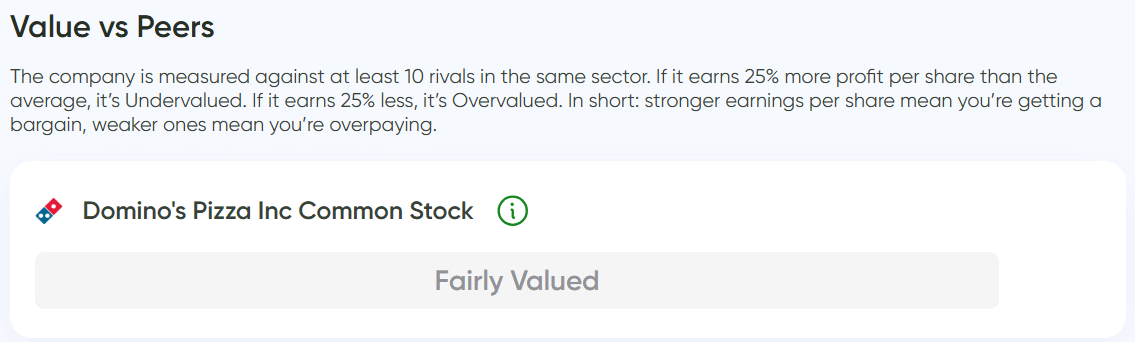
Value vs. Peers — compares Domino’s profitability with other companies in the industry.
Value vs. History — compares today’s valuation with the company’s own long-term average.
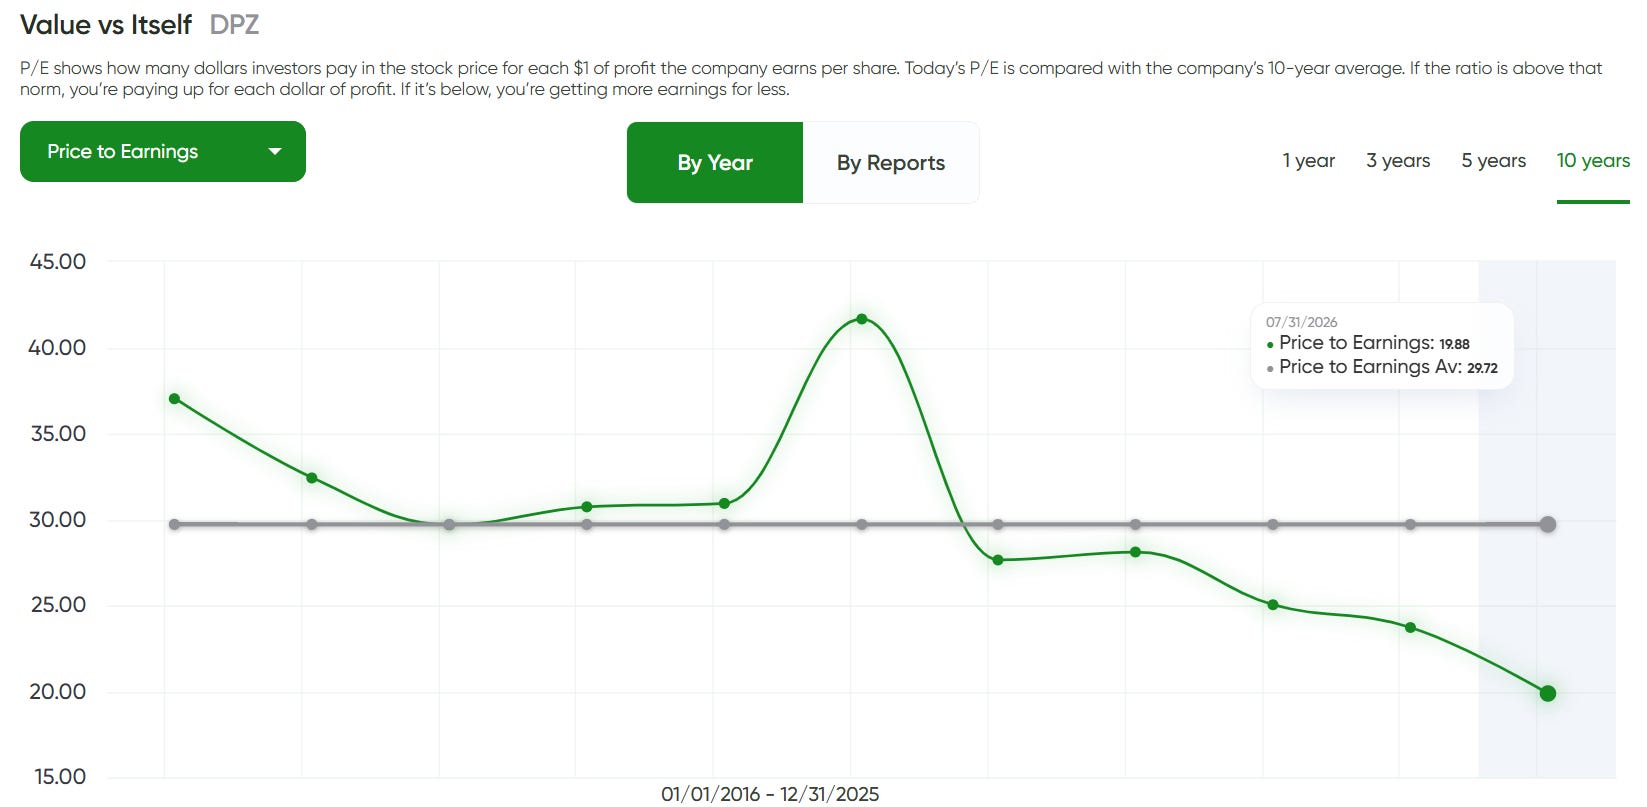
Together, they suggest the stock is trading around a reasonable valuation rather than at an extreme premium or discount.
✅ DPZ - Fairly Valued.
Today, the MaxDividends Research Platform rates Domino’s as Fairly Valued.
Two More Things I Personally Look For
Beyond the platform scores, there are two filters I rarely compromise on.
1. A long history of dividend growth
Domino’s has paid dividends for 13 years and has increased its dividend every single year since initiating it. That’s exactly the type of consistency I want in a long-term income portfolio.
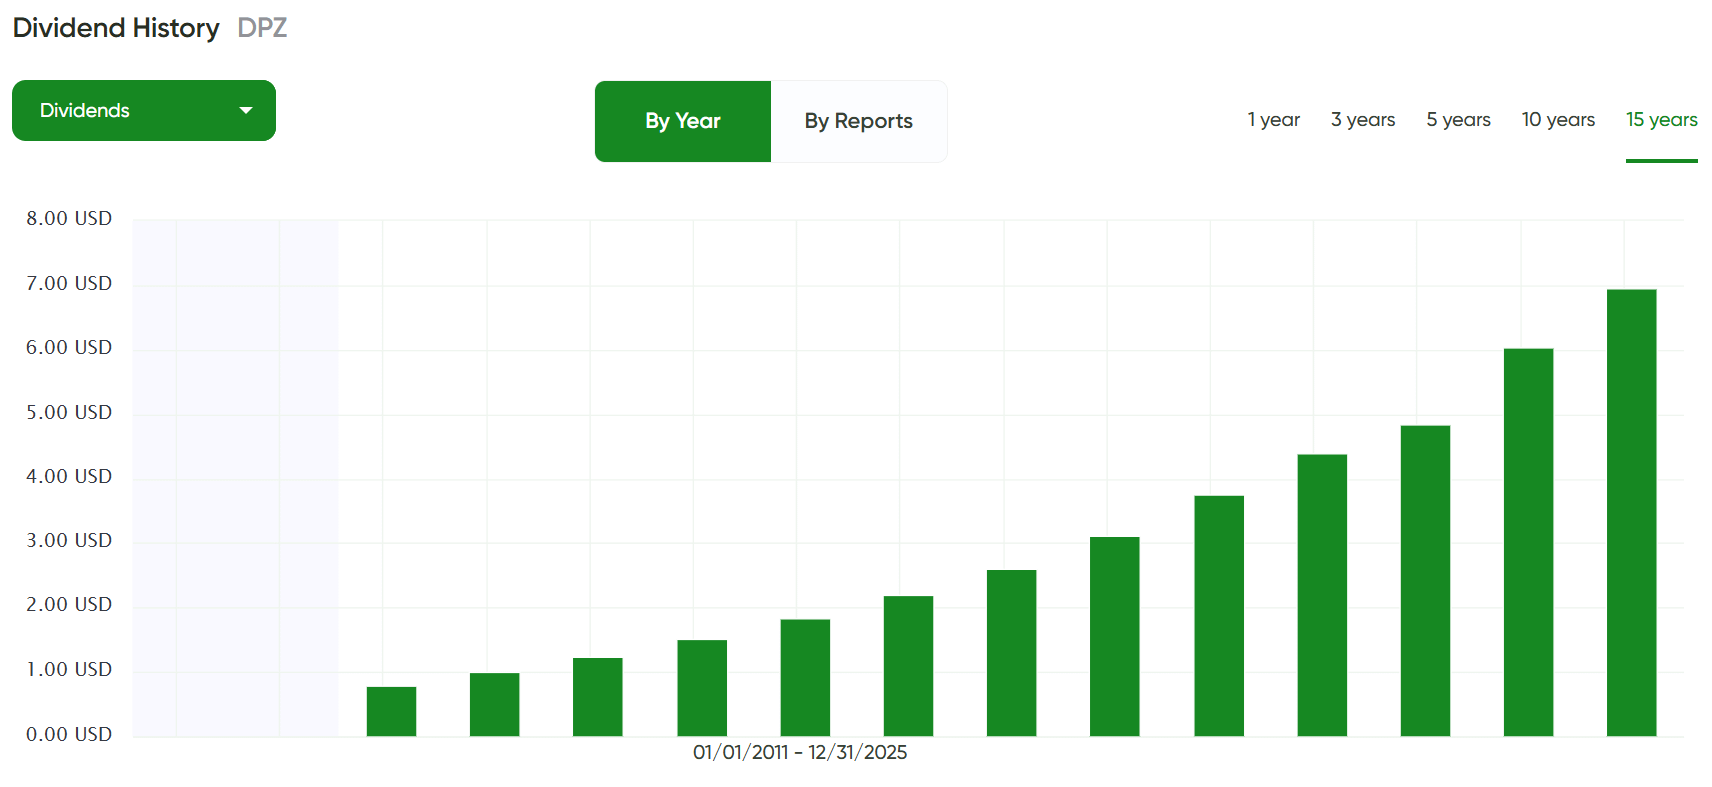
2. MaxRatio 10+
MaxRatio is a proprietary MaxDividends metric designed to identify companies with strong long-term dividend income potential.
It combines:
current dividend yield;
dividend growth over the past 3, 5, and 10 years;
Business Quality Score;
Dividend Safety Score.
Higher MaxRatio companies have historically shown the strongest combination of dividend growth and business quality.
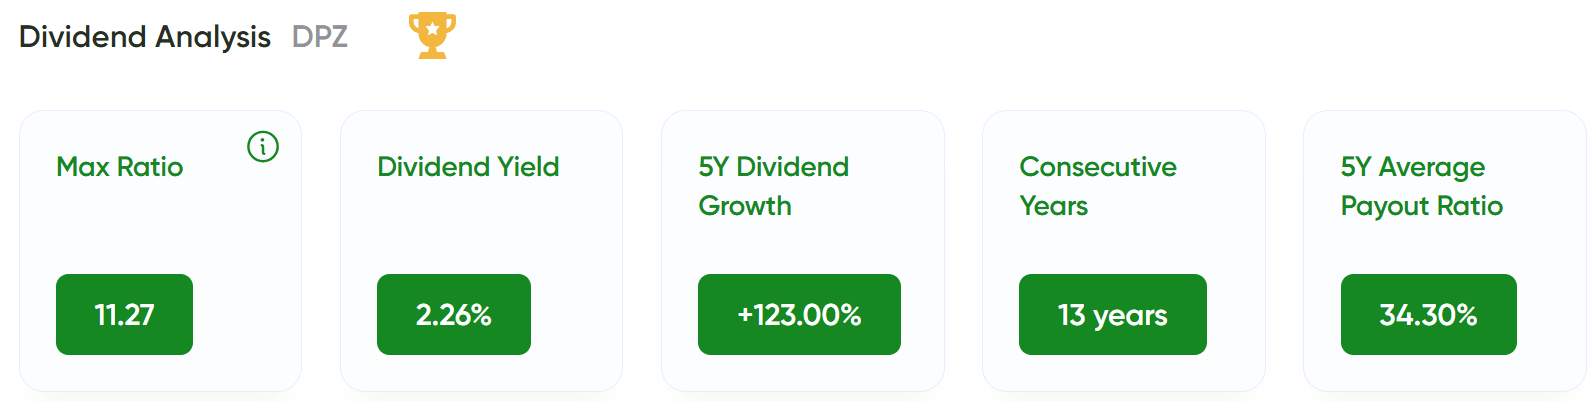
Domino’s comfortably meets that requirement.
Final Verdict
🟢 Max’s Consensus: PLAYING

Every company in the MaxDividends Research Platform falls into one of three categories:
🟢 Playing — high-quality businesses worth actively considering.
🟡 Watching — strong companies, but waiting for a better opportunity.
🔴 Skip — companies that don’t currently meet our quality standards.
Domino’s Pizza earns a clear Playing rating.
Bottom Line
We hope you found this idea as interesting as we did.
But no matter which framework you use—or what decision you ultimately make—always put your own goals first. Take your time, do the work, and invest with care.
Our shared goal is simple: build a growing stream of dividend income that can become a dependable source of financial independence, help cover everyday expenses, and eventually give you the freedom to live on your own terms.
Whether you’re just getting started or already well on your way, Dave and I sincerely hope you keep moving forward.
May the dividends pay the bills!
— Dave & Max
Founders, Dividend School | MaxDividends
The frameworks converged on quality and split on price, which is the informative part. Both screen for stable, growing, well-covered cash flow, so an asset-light royalty model was always going to score highly on each. That agreement is close to structural. Where they diverge, one calling it mispriced and the other fairly valued, is where independent judgement actually sits, since valuation is the input where the two systems weight different things. The split is the real output of the exercise.
The real signal is the franchise-royalty model itself — a company that collects fees on $20B of system sales while only booking $5B in revenue has an asset-light, high-margin structure that scales dividend growth independent of raw volume, which is exactly why a 13-year unbroken raise streak and a MaxRatio north of 11 line up here.