

Hi everyone!
The Fed raised rates on September 16, its first hike since 2023, and the 10-year Treasury ended the month above 5%. Dividend stocks did not enjoy that. Since our September Best Buys on the 3rd, Realty Income is down 10%, Brown & Brown 17%, and Casey’s 20%.
The machine kept paying anyway. Zero cuts. Microsoft, McDonald’s, and VICI all rose, and McDonald’s made it 50 straight years, becoming a Dividend King.
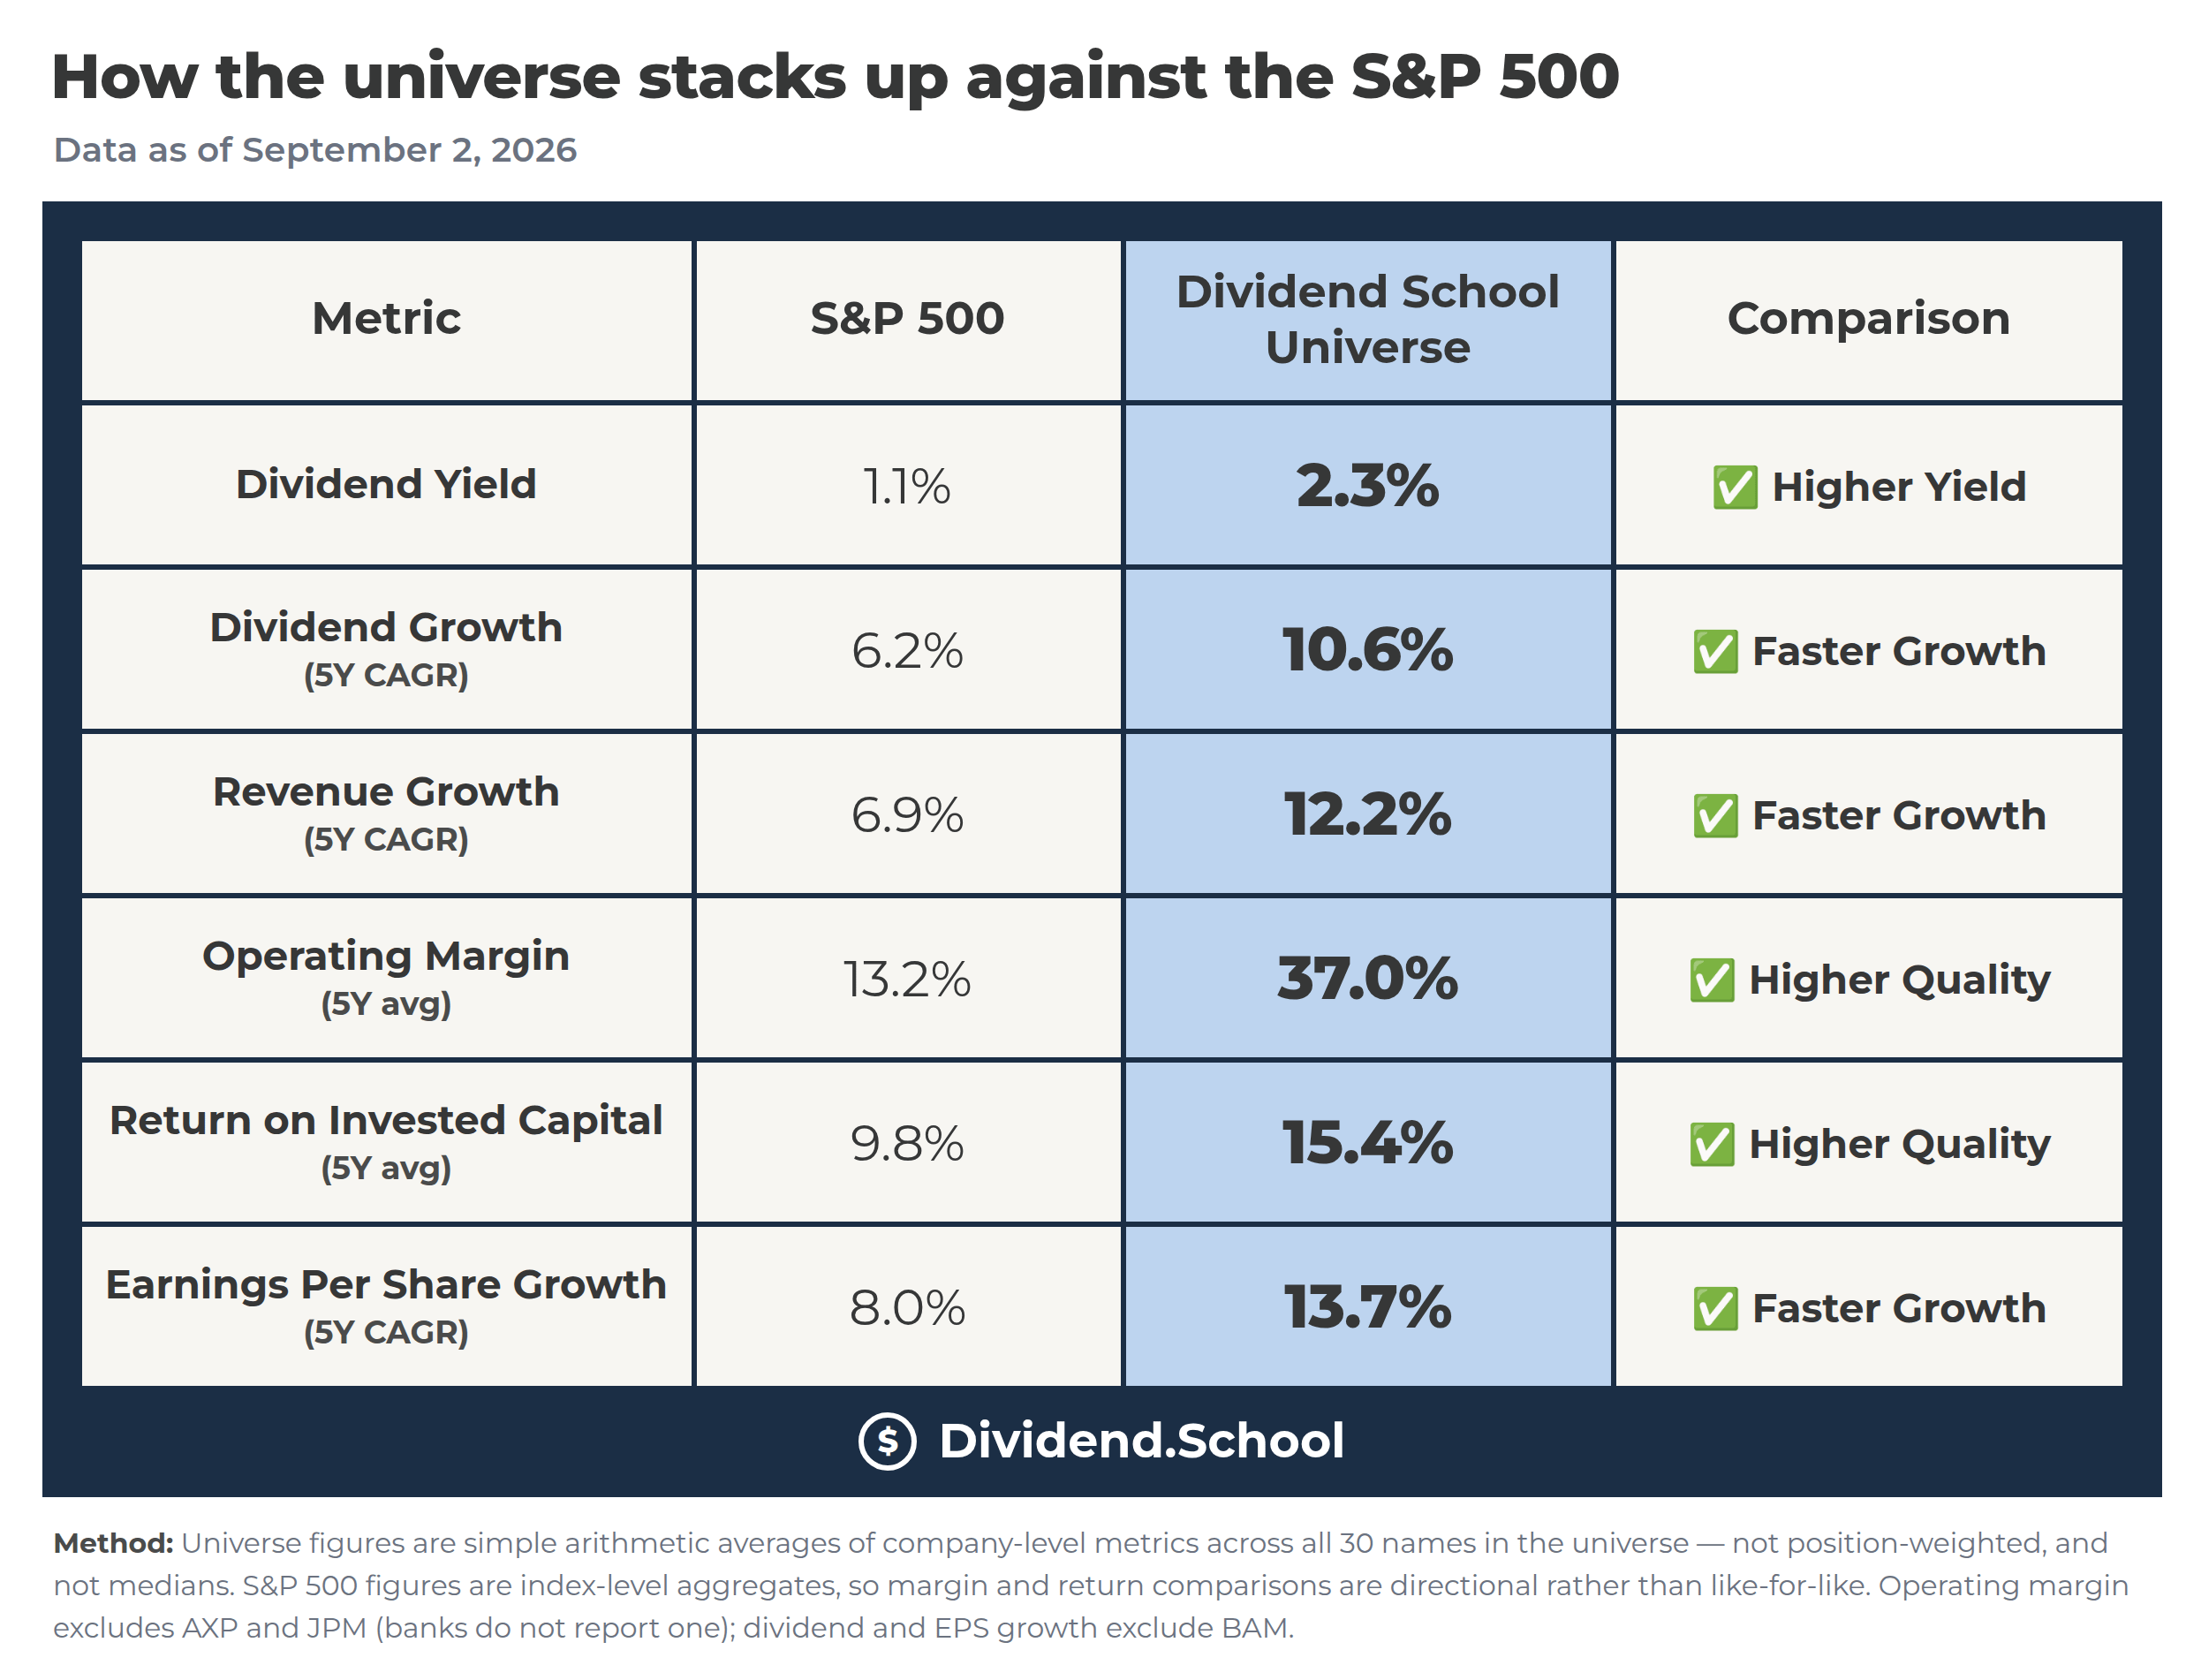
The Universe also grew. Carlisle, Lowe’s, Broadridge, WM and Main Street joined on September 26, and we are now 35 names. This week I re-ran the valuation on all 35, so every name has a fresh Buy Below.
And on October 1, Accenture reported. We have been waiting on this one since July.
In today’s issue, we will discuss:
Accenture: grading the four tripwires
What a rate hike does to the Universe
The valuation reset: new Buy Below prices
The raises: three more landed
Report cards: Broadcom, Casey’s and Cintas
The scorecard
The Buy Below watch
Okay, let’s dive in.
Accenture: grading the four tripwires
Some history for newer readers.
Accenture has been one of our Best Buy Now names since July. In our July deep dive, I set four tripwires, the things that would make me change my mind:
Two consecutive quarters of falling bookings
Gross margin below 32%
Payout ratio through 55% without earnings growth
A dividend raise below 5% in September
Tripwire #1: bookings.
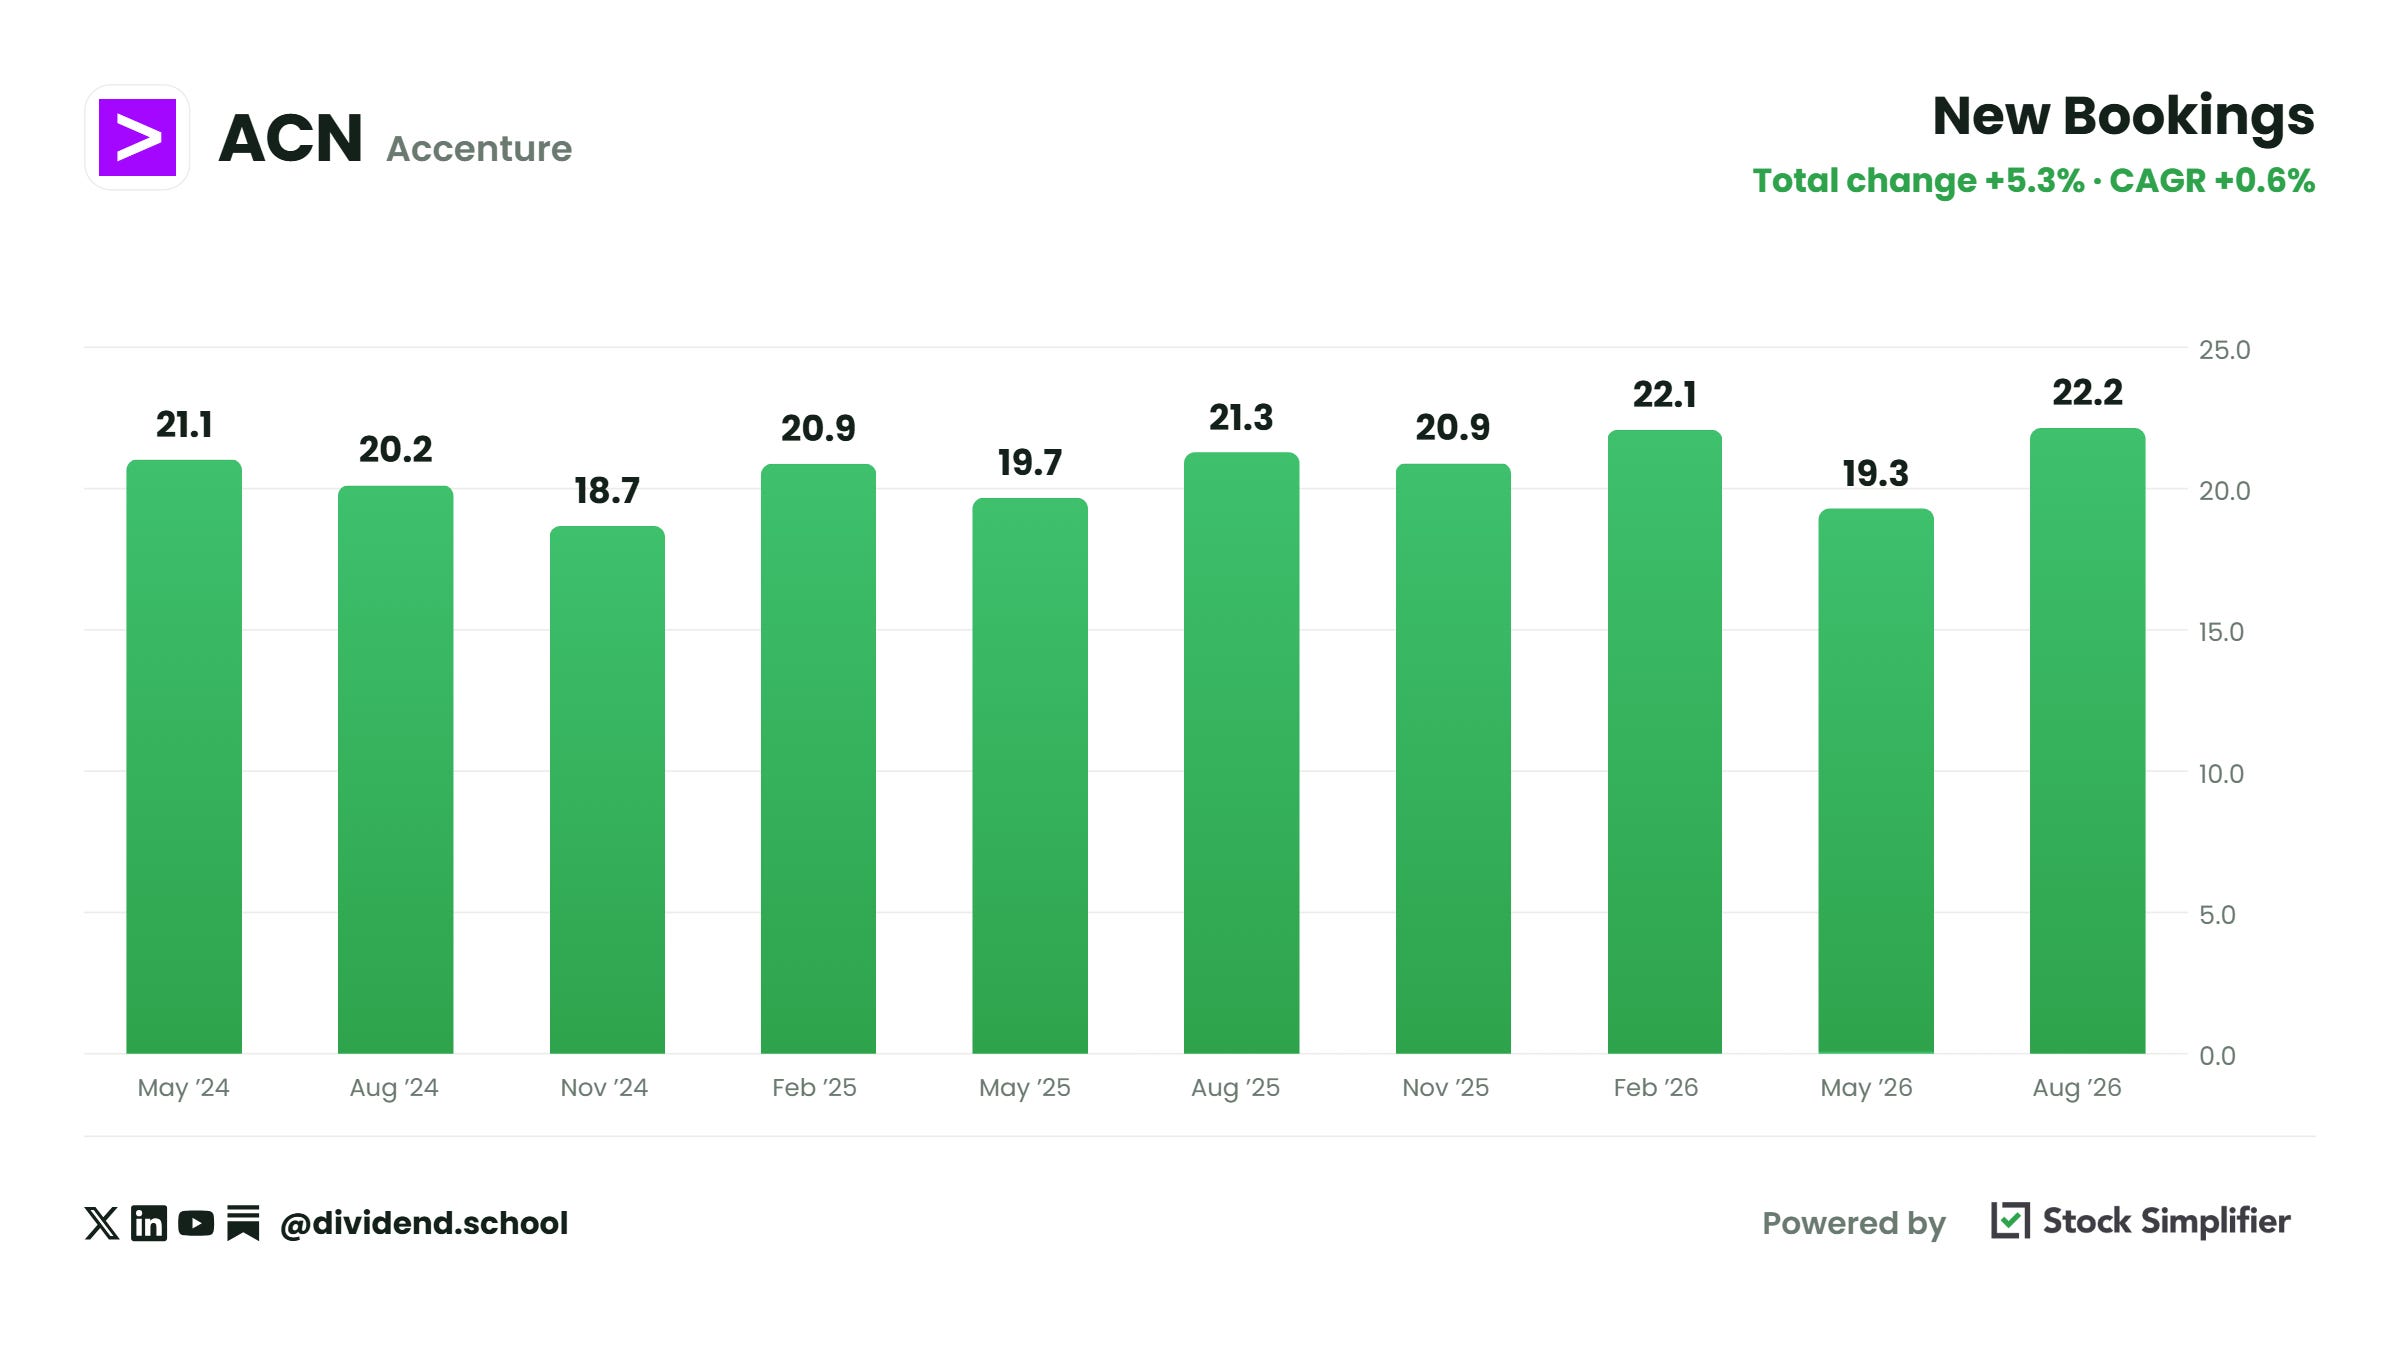
New bookings are the contracts Accenture signed during the quarter, the work it will bill for later. Falling bookings today mean falling revenue tomorrow, which is why we put them first on the list.
Here is the run-up to October 1:
Q4 FY25: $21.31 billion
Q1 FY26: $20.94 billion
Q2 FY26: $22.11 billion
Q3 FY26: $19.32 billion
Q3 was down, at $19.32 billion versus $19.7 billion a year earlier. The quarter before it was up. So that’s one, and the tripwire needs two in a row.
So did Q4 make it two?
No. Bookings came in at $22.17 billion, up 4% from $21.31 billion a year ago (5% in local currency). Accenture signed $1.20 of new work for every dollar it billed in the quarter.
Back to growing, which is what we wanted.
Tripwire #2: gross margin
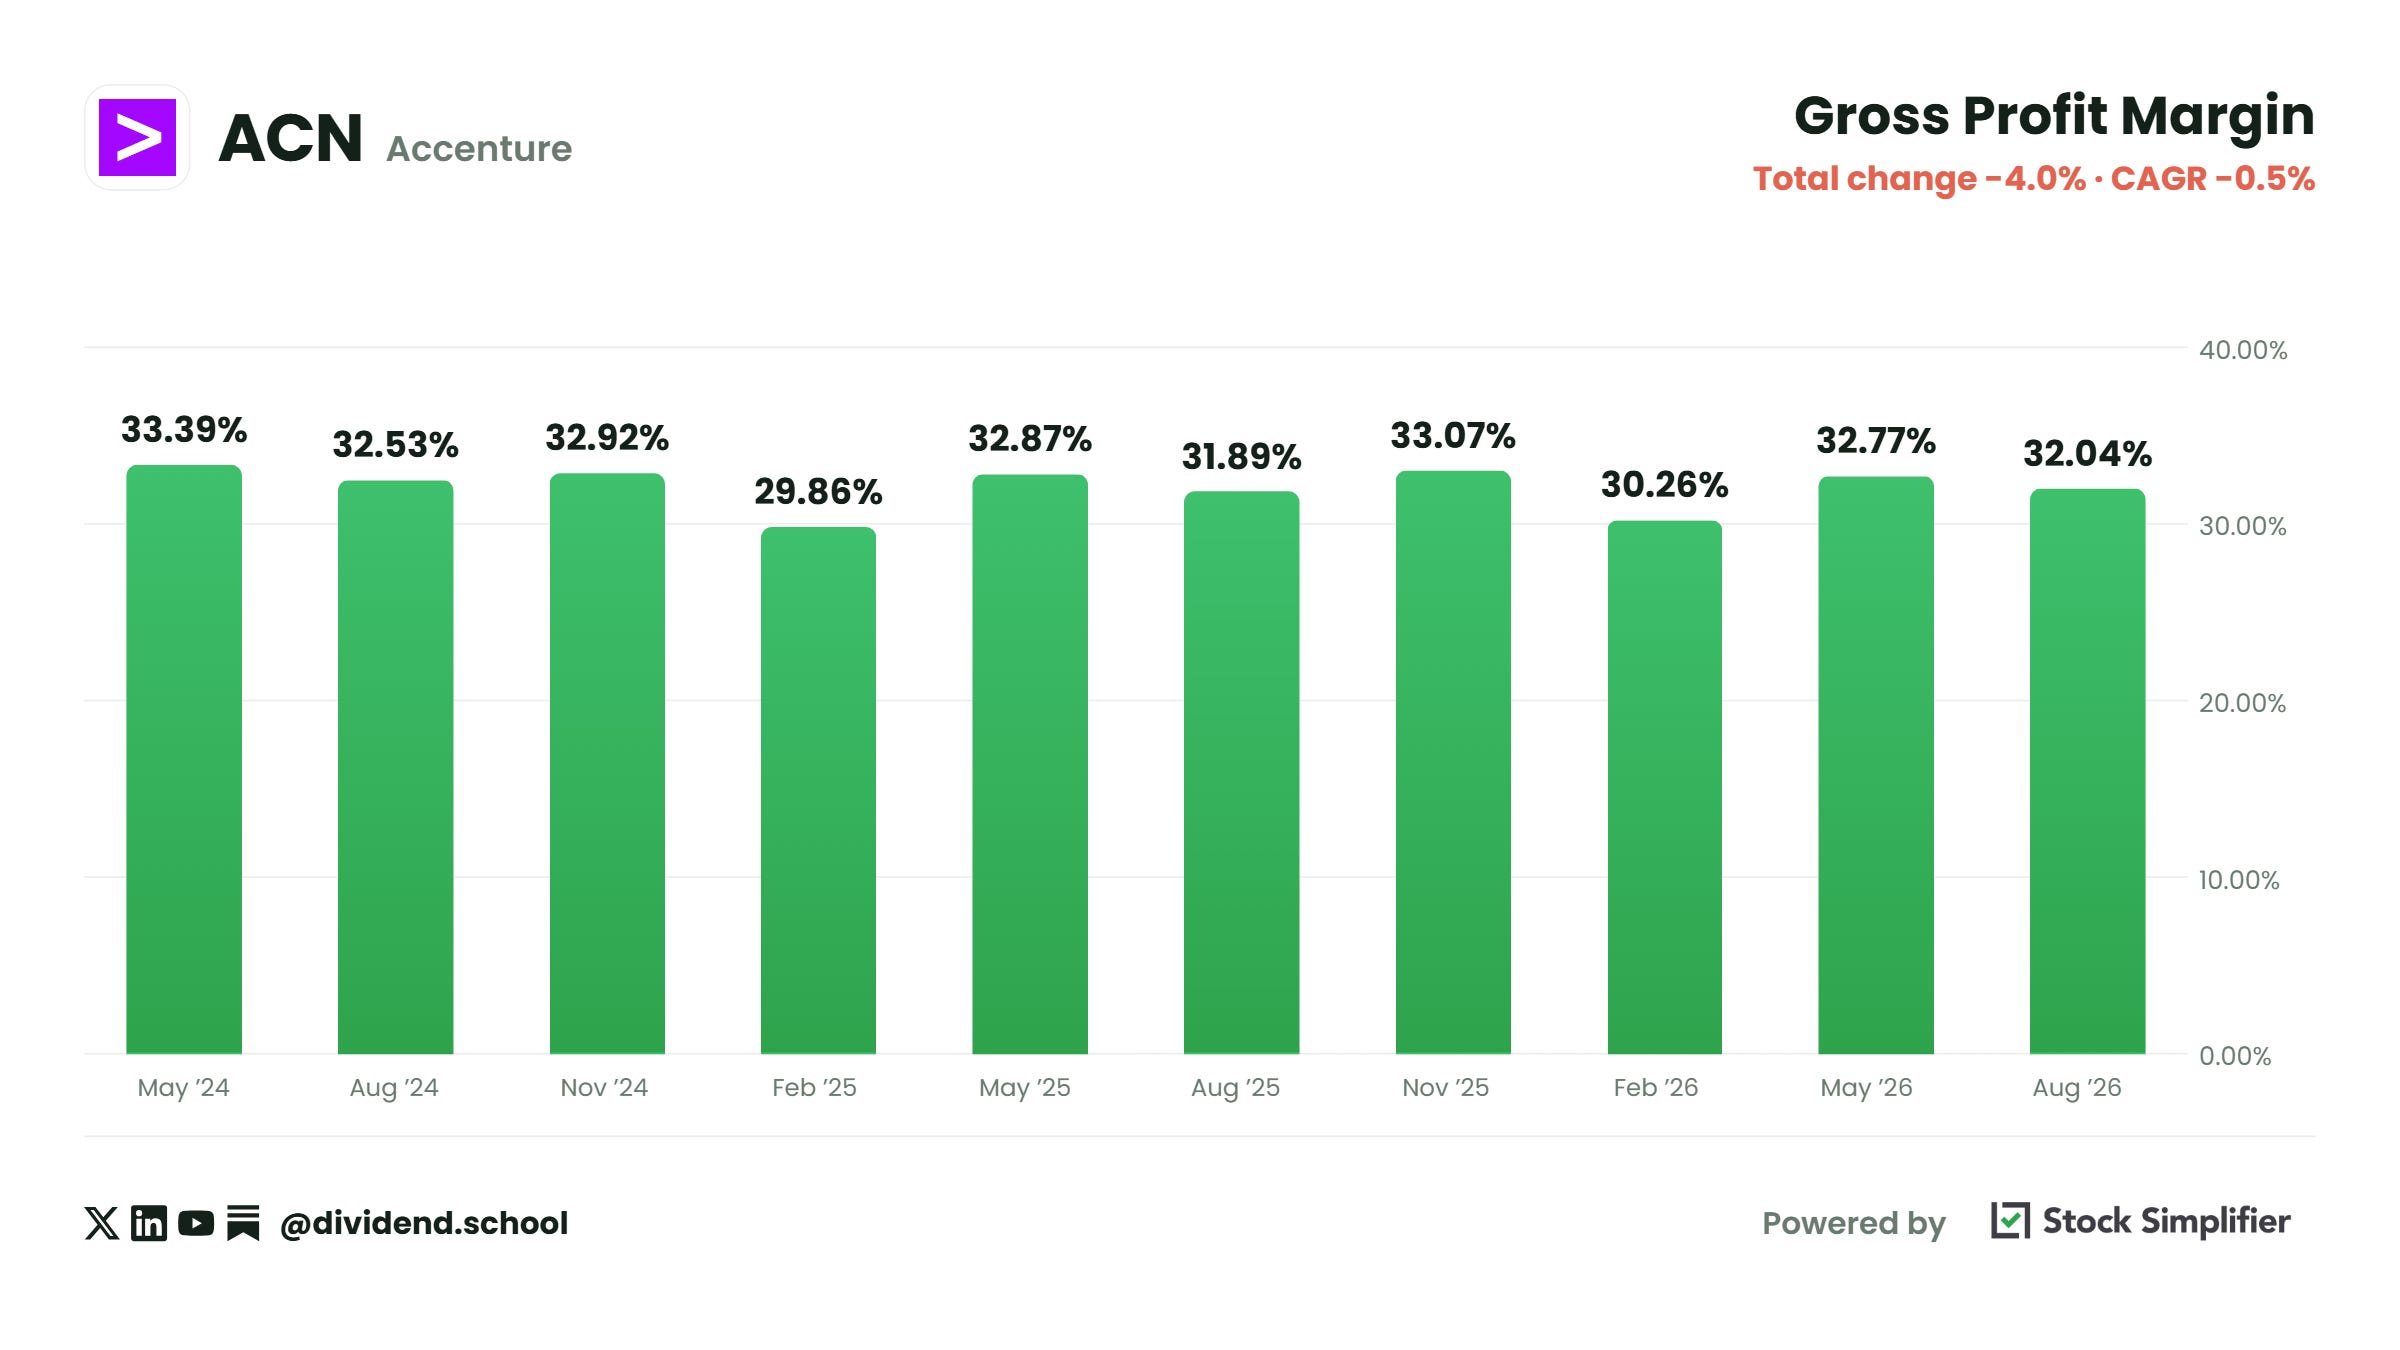
Gross margin is what’s left of each revenue dollar after paying the people who do the work (revenue minus cost of services, divided by revenue).
Q4 FY25: 31.89%
Q1 FY26: 33.07% (32.92% a year earlier)
Q2 FY26: 30.26% (29.86% a year earlier)
Q3 FY26: 32.77% (32.87% a year earlier)
Q4 FY26 is the one we watch, because last year’s fourth quarter already slipped under 32%.
The fourth quarter came in at 32.04% ($5,984.8 million of gross profit / $18,679.1 million of revenue), up from 31.89% a year earlier. That clears the reworded test, and it's back above 32% on the old one too. The full year landed at 32.05%, up from 31.91%.
Tripwire #3: payout ratio
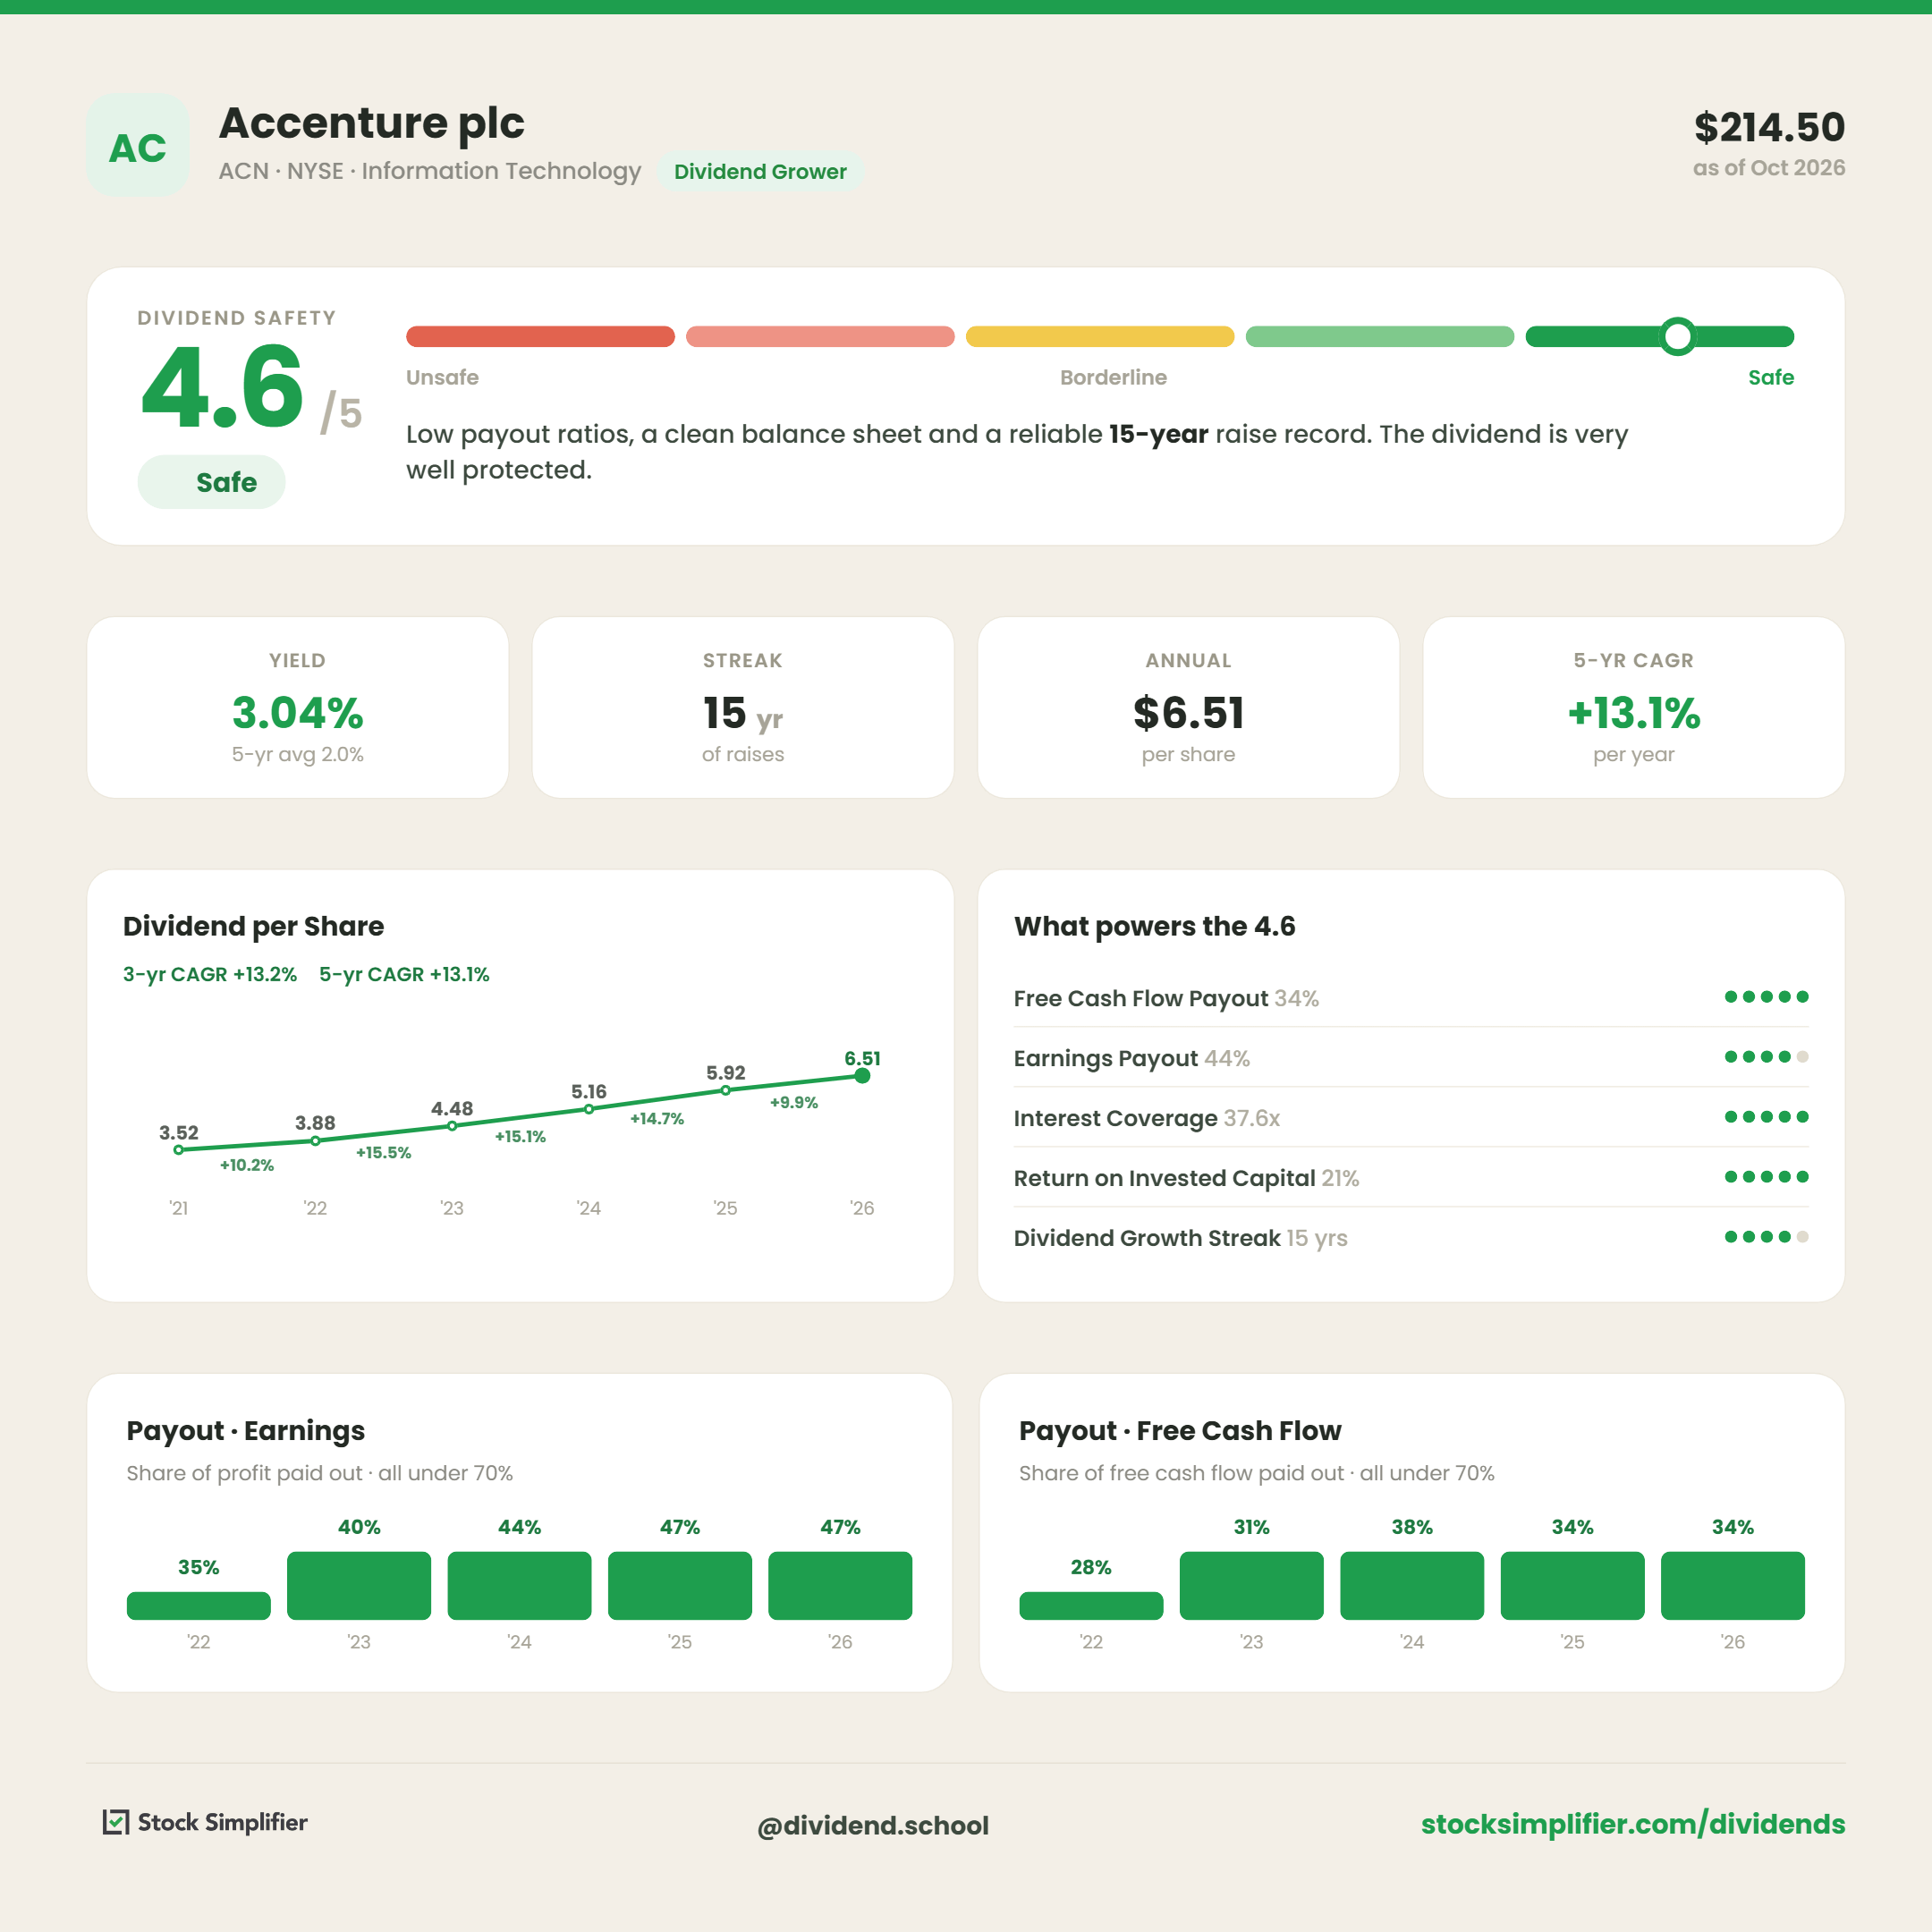
Accenture pays $1.63 a quarter, $6.52 a year. Over the last twelve months through Q3 it earned $12.52 a share (GAAP).
Payout ratio going in: 52.1% ($6.52 / $12.52)
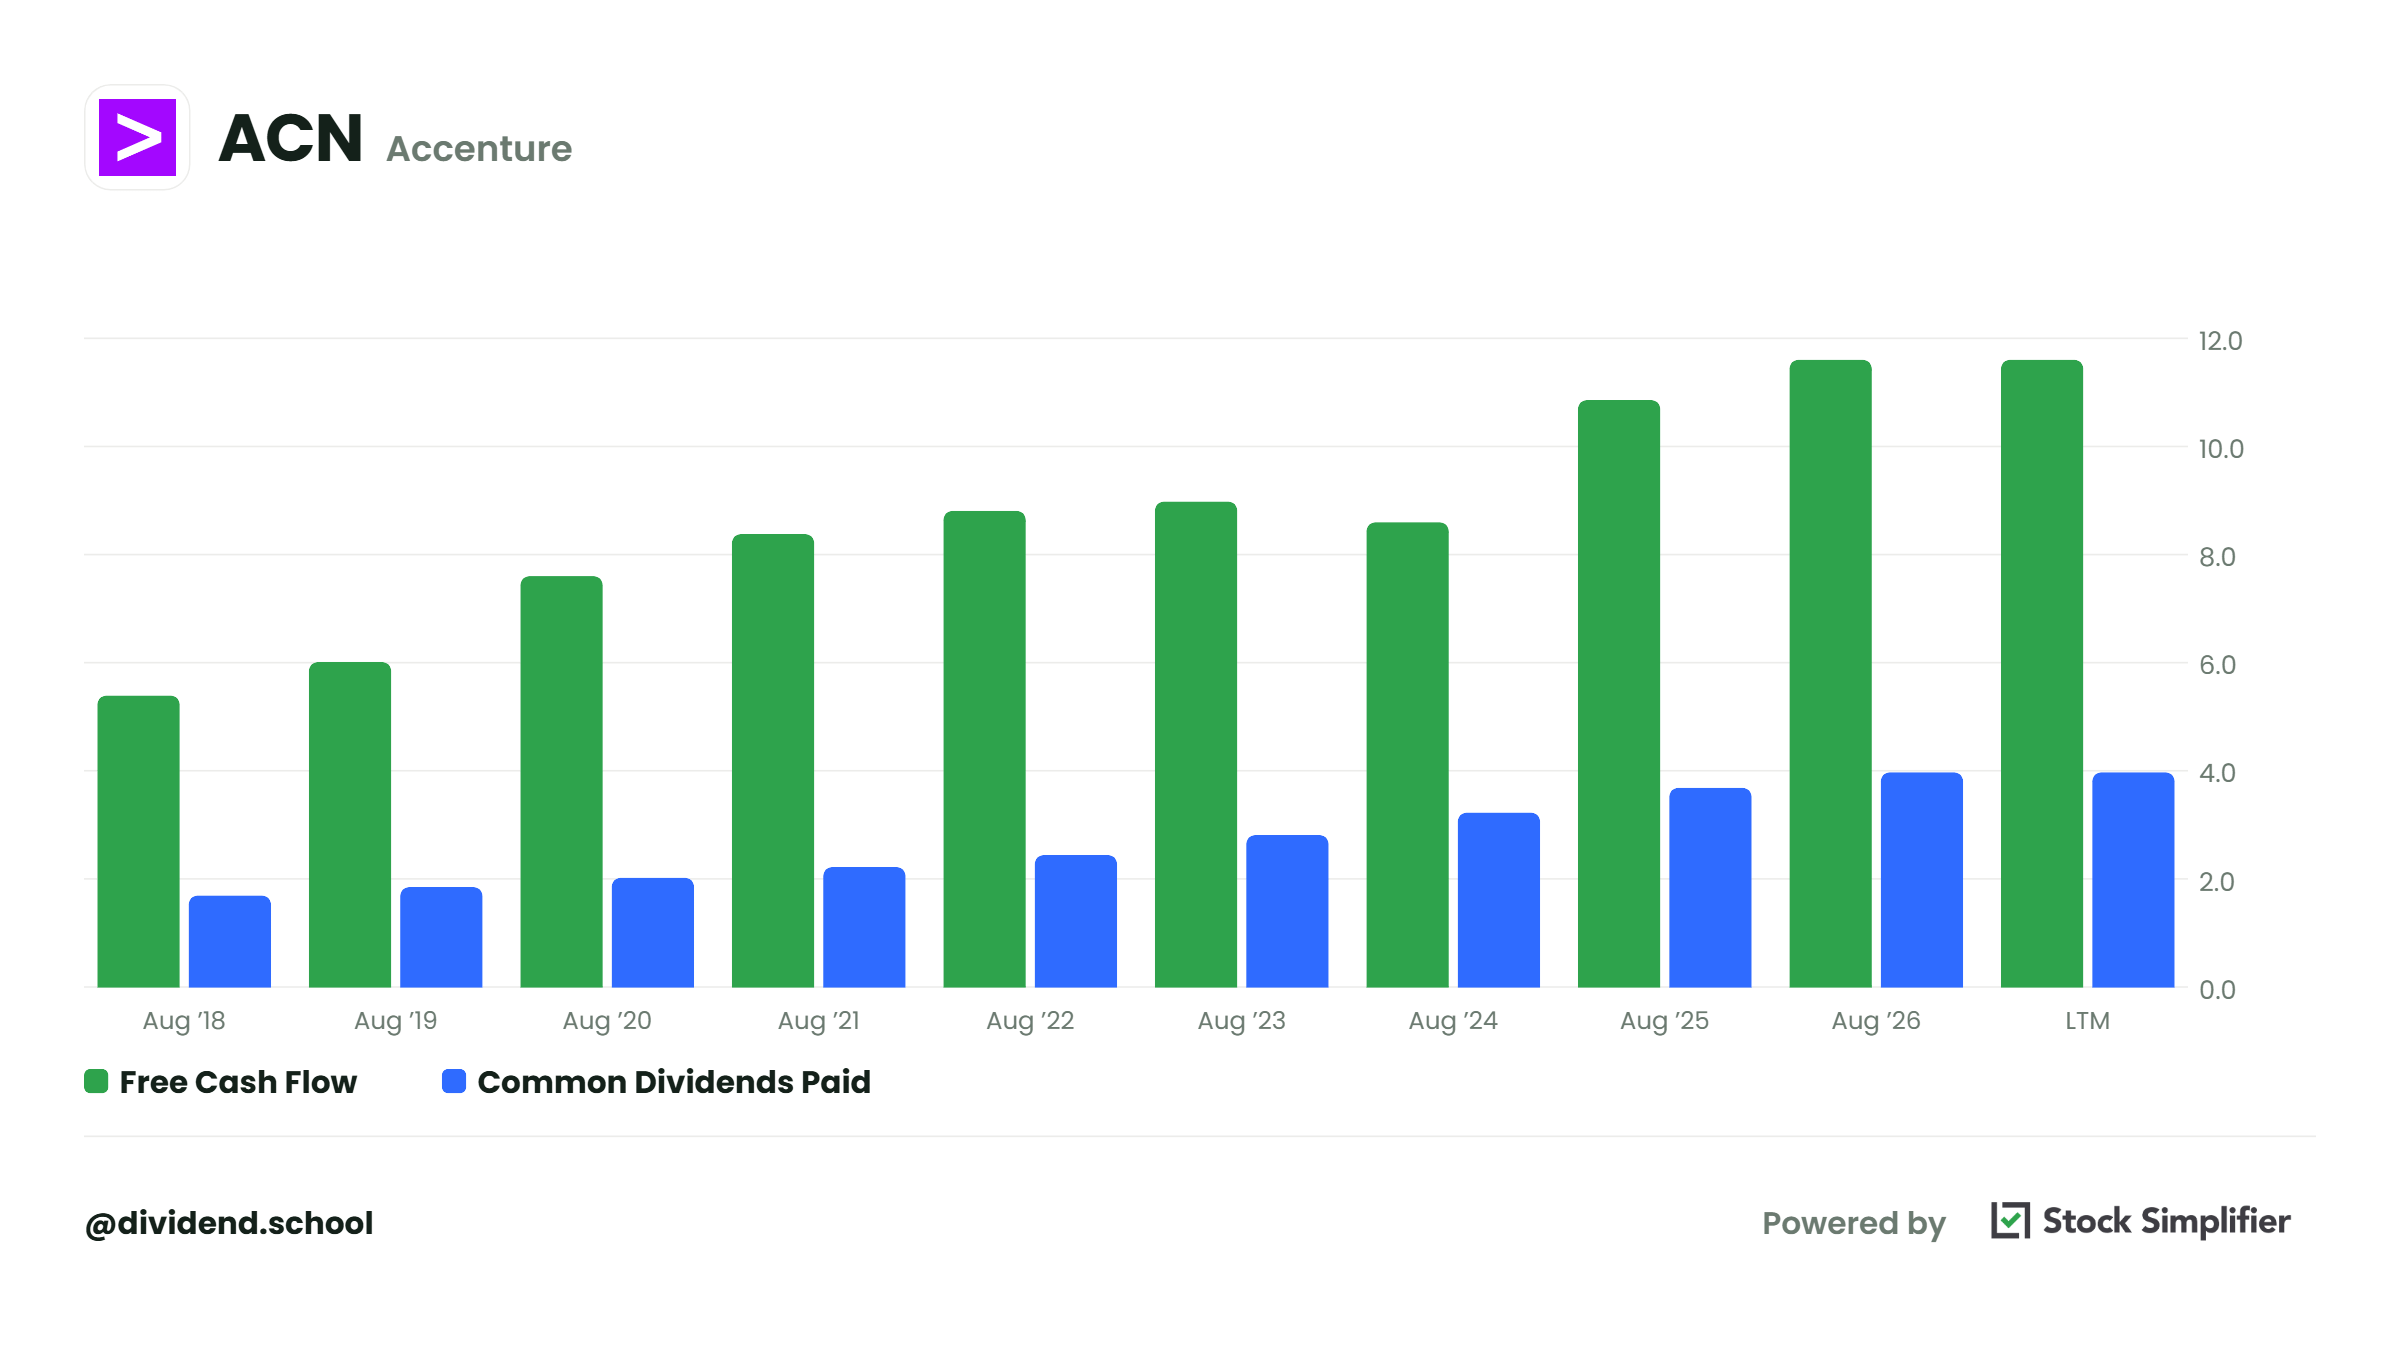
Free cash flow, first nine months of FY26: $8.78 billion
Dividends paid over the same nine months: $3.01 billion, 34% of free cash flow ($3.01 / $8.78)
Measured on free cash flow, we’re well covered. On earnings, 52% is a good number, and regardless of the dividend raise, I feel good about the coverage.
The new dividend is $1.71 a quarter, $6.84 a year. FY26 earnings came in at $13.56 a share (GAAP), up 11.6% from $12.15.
Payout ratio now: 50.4% ($6.84 / $13.56)
Free cash flow, FY26: $11.62 billion, above the top of the $10.8 to $11.5 billion guide
Dividends paid, FY26: $3.99 billion, 34% of free cash flow ($3.99 / $11.62)
The payout ratio went down, not up. Clear.
Tripwire #4: the raise
The last two raises:
September 2024: $1.29 to $1.48, up 14.7%
September 2025: $1.48 to $1.63, up 10.1%
Below 5% trips it.
$1.63 to $1.71, up 4.9% ($1.71 / $1.63). Accenture’s release calls it 5%. The math says 4.9%.
By the letter of the tripwire, it tripped. By a tenth of a point.
The new dividend is payable November 13 to shareholders of record on October 13.
The five questions
How did the quarter hold up against the five questions we ask every company?
Did free cash flow cover the dividend with room to spare? Yes. 2.9 times ($11.62 billion / $3.99 billion).
What did guidance do? FY27 calls for 3% to 6% revenue growth in local currency, $14.39 to $14.81 of earnings per share (6% to 9% above FY26 GAAP), and $11.0 to $11.8 billion of free cash flow.
Where is the payout ratio headed? Down. 52.1% going in, 50.4% now, and 46.8% on the middle of next year’s earnings guide ($6.84 / $14.60).
Are margins holding? Yes. Operating margin was 15.4% for the year, up from 14.7% (15.8% adjusted, up from 15.6%), and FY27 guides to 15.9% to 16.1%.
Is capex crowding the payment? No. $742.7 million in FY26, up from $600.0 million, which is 1% of revenue. FY27 guides to $900 million.
Verdict for our process
One tripwire out of four, and it tripped by a tenth of a point.
Bookings grew, margins grew, the payout ratio fell, and free cash flow beat the top of the guide. I’m not going to pretend 4.9% is 5%, so the tripwire counts, and we’ll hold Accenture to a higher bar on next year’s raise. But a raise that misses by a tenth of a point, paid out of a falling payout ratio, isn’t a reason to sell.
Accenture stays a Buy. At $214.50 as of Thursday, it sits 6+% below the $227.35 Buy Below.
That’s Accenture, graded in full. The same treatment for the rest of the Universe is below.
That’s Accenture, free.
Below the line: the three raises since Issue #3, each measured against that company’s own record, and one of them came in at 2.2%, down from 4.0% last year. Report cards for Broadcom, Casey’s and Cintas. What the Fed’s hike did to our REITs, our utilities and the ratings agencies. A fresh Buy Below for all 35 names, including the five new ones, and two of those five go straight to Best Buy Now.
Casey’s beat on earnings and fell 14% the next day. I would read that section first.
Members, keep scrolling. Everyone else, seven days free.
$369 a year or $35 a month. Thirty-day money-back guarantee either way.